Printed 2026 · figures read October 2026
Apple Pay casino deposits add £0.00 to the price of the bonus
What the tap adds to the price of a bonus. The floor stands where it stood, the credit is the credit the terms name, the counter reads the same multiple, and no charge attaches to the payment either way. What the wallet does alter is what travels: the real card number stays on the device and a stand-in reaches the cashier. Sources: the wallet’s own security pages, read 13 October 2026.
Where a tap is accepted, and the cashier behind each offer
Every link in this rack is a paid placement, and this site is owed a fee when a reader opens an account through one.
Betportal
Lowest wagering
Licence Licensed in Anjouan, Comoros, no Great Britain licence, run by BetPortal Gaming Ltd and Excite Ultra Media Ltd, reference ALSI-202601040-FI2.
WinBeast
Free bet included
Licence Licensed in Curaçao, no Great Britain licence, operator not named on the site.
EliteSpin
New for 2026
Licence Licensed in Costa Rica, no Great Britain licence, run by PrimeTier Limited, opened 2026.
Crown Jewelz
200% first deposit
Licence Licensed in Curaçao, number not verified, no Great Britain licence, operator not named on the site.
Scroll the rack sideways to reach the other columns. The label column stays put.
Not one of the offers printed above holds a Great Britain licence. Outside that licence a British player has none of its protection: Gamstop Online cannot shut the door, the ten-times limit on bonus wagering does not bind the operator, and no British complaints body will take up a dispute. You must be 18 or over to open an account anywhere in this rack.
Every figure in the rack is a term the operator itself publishes, read on 14 October 2026. The operator's terms in full are the ones that bind you.
£20 by tap, in pounds per pound
| What these offers ask | Under a British licence | |
|---|---|---|
| You put in | £20.00 | £20.00 |
| Handed over | £20.00 | £20.00 |
| Wagering | 40x | 10x |
| Cost per £1 kept | None remains | £0.67 |
A tap is a card payment with a different number on it, so every row here would read the same if the card had been typed in by hand. Worked where each pound staked returns 96 pence and no round counts short. Staking of £800 against £20 of credit hands £32.00 to the games, which exceeds the credit, so nothing remains to put a price on. Drop the counter to the British ten and the retention is £8.00, £12.00 remains, and 67p of expected cost sits behind each pound of it. A counter held to ten is a condition of the Great Britain licence, and the register behind a site of this kind reads Costa Rica, Curacao or Anjouan. The one financial question the wallet does raise, which is whether the card inside is a credit card, is answered by the licence and not by the phone.
01
The widest door in the cashier, and the narrowest effect
No route in this section is accepted more widely, the two card networks aside, and offers of this kind carry it almost without exception. That makes sense, because the wallet is those same networks wearing a different number.
£0.00 is what the tap adds to the cost of a deposit, and nothing in the strip above moves because of it. The floor stays at £20 or €20, a full match still credits £20, the counter still reads 40 times, and the games still keep £32.00 of the £800 they are asked for.
What does change is the number that leaves the phone, and that is worth four paragraphs rather than a sentence, because it is security rather than price and the two are easily confused.
The networks underneath are priced at visa casino and mastercard casino. The other phone wallet, carried a good deal less widely, is at google pay casino. The card type question goes to credit card casino, and the whole set of routes sits at how you pay.
02
Four published mechanisms, and not one of them is a price
14 July 2015 is when the wallet reached Britain. Four things it does are published by the maker, and the table sets each against what it actually protects.
| Mechanism | What it protects | Effect on the bill |
|---|---|---|
| A device account number in a secure chip | The card number is not held on the phone | None |
| Nothing real sent to the merchant | The cashier never receives the card number | None |
| A security code made for one payment | A captured code cannot be used again | None |
| No transaction record tied to the user | The maker says it keeps none | None |
Every entry in the right-hand column is the same, and that uniformity is the point of the table. These are protections against interception and reuse. None of them is a protection against a counter of 40 times, a winnings ceiling, or a cashier that will not pay out.
A reader comparing routes on security alone should take the first three rows seriously. A reader comparing routes on cost should look at the fee pages of the wallets and vouchers instead, where real figures exist.
03
A lost phone is a card problem with three published answers
Three routes exist for shutting the wallet down and they are published together. Putting the device into its lost mode suspends the wallet. Cards can be taken off through the finder service, through the wallet application itself, or through the maker’s website.
What happens next belongs to the card rather than to the phone. Suspending or revoking the payments is the issuer’s act, or the network’s, and it holds whether or not the device is online, because that authority lies with whoever issued the card.
So the honest summary of a lost phone is that the phone is a container. Emptying the container is quick and the three published routes are the way to do it, but the thing that stops the money moving is the same institution that would stop it if the card had been in a wallet in a coat pocket.
That matters here for one reason. Documents are wanted before a first payout at sites like these, so an account opened by tap has an identity step waiting at the exit. A phone that has gone missing does not pause that step, and nothing on this page helps anybody past it.
04
The card inside settles every question that costs money
Whatever card is loaded is the one that pays, so loading a debit card gives a debit payment and loading a credit card gives a credit one. Britain’s condition on the credit route is addressed to licensees, which is why a licensee has to satisfy itself that money funded on credit cannot come in through a wallet at all.
A bank’s own card gambling block also reaches a tap, because what a block examines is a card payment to a merchant tagged as gambling. The tag travels with the payment and the stand-in number does not remove it.
Two things follow for a reader who has set controls. A block switched on will stop a tap to any of these cashiers, wherever they are licensed, because the tag is what it reads. And a payment routed through an intervening balance, such as a wallet with its own account, can escape that reading, which is an argument for the tap over the detour.
None of that changes the offer. The three figures a buyer acts on in this trade are the credit, the counter and the clock, and a phone touches none of them.
05
Every brake on a gambling payment publishes its own wait
48 hours is the shortest published wait before a lifted brake stops applying, and 72 hours is the longest among the four below.
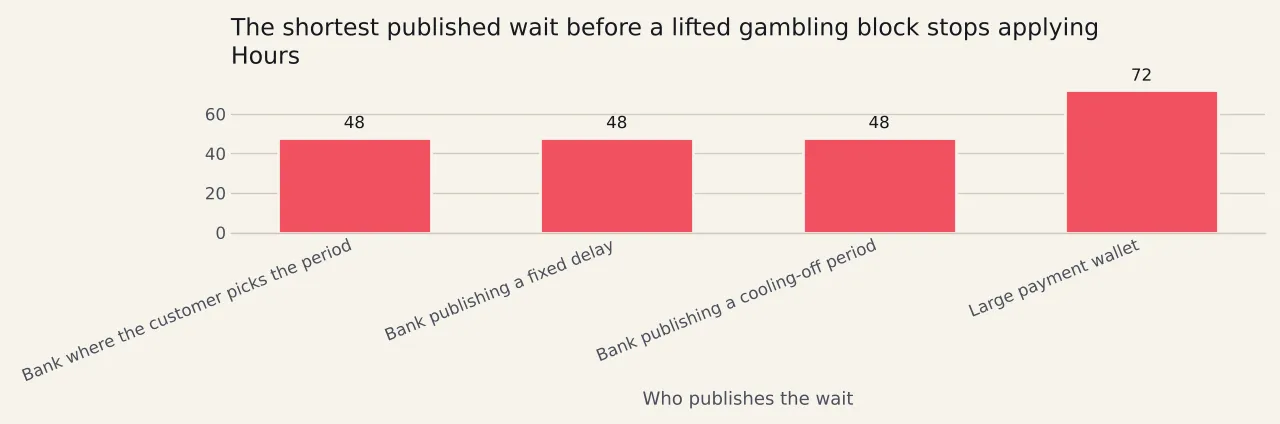
Scale matters here more than the differences between the bars. 48 hours is two days of friction. A year is 8,760 hours, and one bank publishes exactly that as the top of its own range, which is 182 and a half times the floor.
Figures for take-up exist at one bank and nowhere else. On that bank’s own count its brake has been used by upwards of 700,000 customers, and it puts the share of banks offering the feature at around 90 per cent, which is its claim rather than a published market figure.
06
The one figure a licence would move
£32.00 becomes £8.00. That is the whole of what the licensed side changes about a £20 tap, and it comes from the counter rather than from the payment.
Around it sit the protections with no price. The national self-exclusion scheme reaches an account because of the British licence behind it, so registering closes a licensed cashier and leaves the offshore side open. A complaint at a licensed cashier has a published route and a deadline, and ends with an independent body named. A licensed cashier settles identity before play rather than before a payout.
A licensed cashier also owes a reader something during play that offers of this kind do not: net spend and time elapsed, shown in real time, a duty running since 17 January 2025.
Against all of that, the tap is unchanged on both sides. The same mechanisms, the same stand-in number, the same nil effect on the bill. A phone wallet is a better way to hand over a card number and it is not a better offer.
07
What the tap adds, and what the credit costs
Six lines. The first three count what the phone contributes and the last three price what the money buys.
A £20 tap at a 40 times column
- Real card numbers reaching the cashier 0
- Payments each security code is good for 1
- Added to the deposit by the phone £0.00
- Credit a full match puts beside it £20.00
- Staking the counter asks of it £20.00 × 40 = £800.00
- Kept by the games, where ten times keeps £8.00 4% of £800.00 = £32.00
Lines one to three are the honest sum of what a phone wallet contributes to a price, which is nothing, and lines four to six are the arithmetic it cannot touch. At ten times the counter asks £200.00 and the games keep £8.00, so £12.00 of the credit remains at 67p a pound; that is the licensed reading of the strip above. Outside the sum sit the published terms that cut the figure further: five times the credit as a winnings ceiling where one is published, seven or fourteen days on the clock in most terms, and reels as the only product that moves the counter. A brake, if one is set, lifts after 48 hours at three publishers and 72 at a fourth, up to a year where the customer picks the length.
08
Questions about paying by phone wallet
- Do offers of this kind take this wallet?
- Almost all of them, which puts it level with the two card networks this trade takes most widely. That is unsurprising, because the wallet pays with one of those networks underneath a stand-in number. The other phone wallet is carried a good deal less widely.
- Does paying by phone make a deposit cheaper?
- It adds £0.00 and subtracts £0.00. The floor stays at £20 or €20, a full match still credits £20, the counter still reads 40 times and the games still keep £32.00 of the £800 asked for. Nothing in the price of the credit depends on how the card number travelled.
- What does the phone actually protect?
- Four published mechanisms, all of them about interception rather than cost: a device account number held in a secure chip, no real card number sent to the merchant, a security code made for one payment only, and no transaction record the maker ties back to the user. None of them is protection against a counter or a winnings ceiling.
- What happens if the phone is lost?
- Three published routes shut the wallet: the device’s lost mode suspends it, and cards can be removed through the finder service, the wallet application or the maker’s website. After that it is the issuer or the network that suspends or revokes, and it holds whether or not the device is online.
- Will a bank gambling block stop a tap?
- Yes, where one is switched on. A block examines a card payment to a merchant tagged as gambling, and the tag travels with the payment, so a stand-in card number does not hide it. A payment routed through an intervening wallet balance can escape that reading, which is an argument for the tap rather than the detour.
- Is a credit card in the wallet still a credit card?
- Yes. Whatever card is loaded is the one that pays, so the type is unchanged by the phone. On the licensed side a licensee has to satisfy itself that money funded on credit cannot come in through a wallet at all, which is why the licence settles the question and not the handset.
- How long does a lifted brake take to stop working?
- 48 hours at three publishers in this section and 72 hours at a fourth. One bank hands the choice of length to the customer instead, two days at the shortest and a year at the longest, and a year is 8,760 hours, which is 182 and a half times the floor. Two publishers note that a payment tagged outside the gambling category can fall outside the brake.
- What would a British licence change here?
- One figure and four protections. The retention falls from £32.00 to £8.00 because the counter falls to ten times. Beyond that: registering a self-exclusion would shut the account; a complaint would travel a route against a deadline; identity would be dealt with before play; and net spend and time elapsed would appear on the screen while playing.